


.jpg)


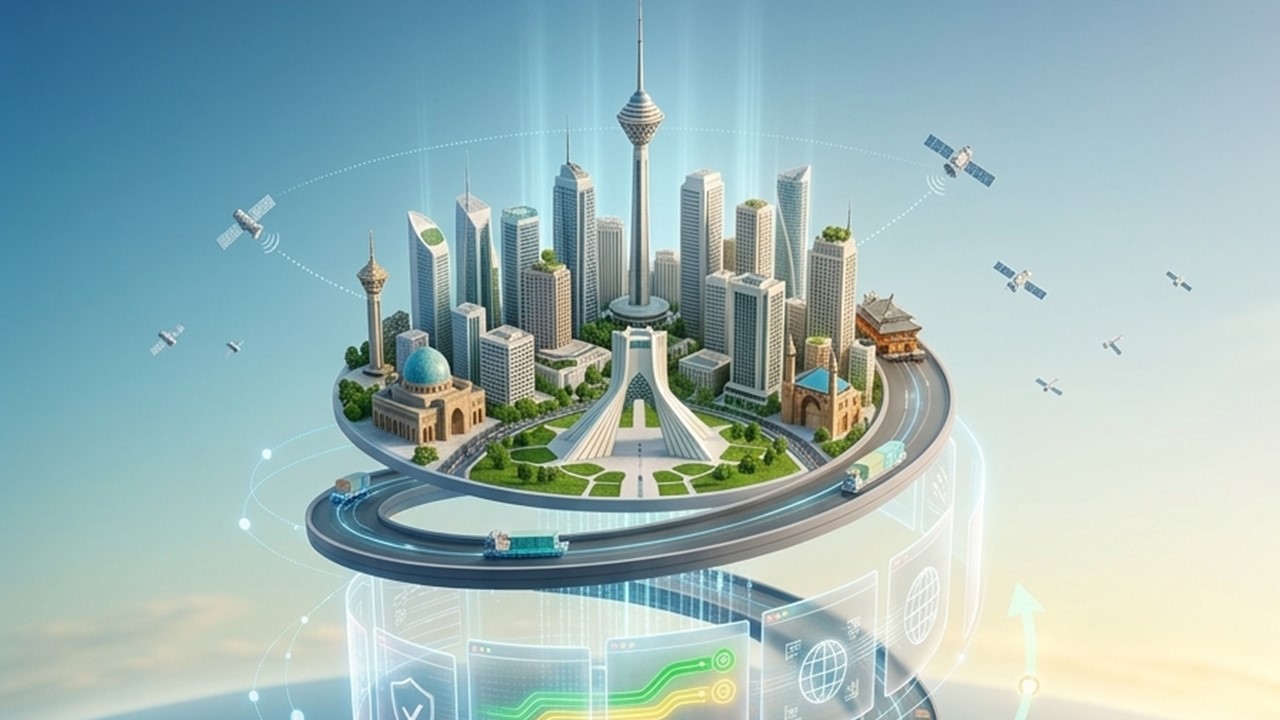
ایران و افغانستان در زنجیرههای ارزش منطقهای ظرفیتهای تجاری، پیوندهای تولیدی و الزامات دسترسی به بازارهای ثالث
 برای دانلود فایل با کیفیت اصلی کلیک کنید

ایران بزرگترین تأمینکننده بازار افغانستان است؛ اما مسئله راهبردی، چگونگی تبدیل این جایگاه به سهمی پایدار از ارزش افزوده تولید، فرآوری و دسترسی به بازارهای ثالث است. یافتههای پژوهش حاکی از آن است که تعمیق روابط اقتصادی دو کشور، در کنار حفظ و گسترش صادرات، مستلزم پیوند میان ظرفیت عرضه مواد اولیه افغانستان، توان تولیدی و تجاری ایران و تقاضای بازارهای منطقه است. در این چارچوب، قابلیت سازماندهی این پیوند، مبنای بهرهبرداری اقتصادی از موقعیت تجاری و کریدوری دو کشور قرار میگیرد.
در سال آماری ۲۰۲۵-۲۰۲۶، واردات افغانستان از ایران به حدود 3.67 میلیارد دلار، معادل 27.3 درصد از کل واردات این کشور رسیده است. در مقابل، صادرات افغانستان به ایران حدود 52.16 میلیون دلار بوده است. این عدمتقارن، غلبه نقش تأمینکنندگی ایران را نشان میدهد. بااینحال، افزایش سهم ایران در قطعات خودرو و کاهش آن در گازوئیل و بنزین، بیانگر تفاوت موقعیت رقابتی کشور در بازارهای کالایی است. بنابراین، ارزیابی پایداری این جایگاه، مستلزم بررسی ترکیب تجارت و تحولات سهم بازار در سطح کالا و رقیب است.
بر این اساس، پیشنهاد پژوهش، سازماندهی زنجیرههای منتخب در چارچوب قراردادی مشخص میان تأمینکننده افغانستانی، واحد فرآوری ایرانی، ارائهدهنده خدمات لجستیکی و خریدار بازار ثالث، پیش از ورود ماده اولیه است. در این الگو، بخش خصوصی مسئولیت تأمین، تولید و فروش را بر عهده دارد؛ دولت از طریق دیپلماسی اقتصادی، پیگیر رفع موانع فرامرزی است؛ و اتاقهای بازرگانی، زمینه شناسایی شرکای معتبر و تشکیل کنسرسیومها را فراهم میسازند. حاصل این رویکرد برای تصمیمگیران، تشخیص بازارهای نیازمند حفظ موقعیت، اولویتهای همکاری تولیدی و الزامات اجرایی پیش از تعهد سرمایه است. معیار این تشخیص نیز سهم دریافتی و قدرت حفظ این سهم توسط بنگاه ایرانی از زنجیره ارزش افزوده خواهد بود.
Iran is the largest supplier to the Afghan market; however, the strategic issue is how to transform this position into a sustainable share of the value added generated through production, processing, and access to third-country markets. The findings of the study indicate that deepening economic relations between the two countries, alongside maintaining and expanding exports, requires linking Afghanistan’s capacity to supply raw materials with Iran’s production and commercial capabilities and the demand of regional markets. Within this framework, the ability to organize such linkages becomes the basis for economically leveraging the two countries’ trade and corridor positions.
In the 2025–2026 statistical year, Afghanistan’s imports from Iran reached approximately $3.67 billion, equivalent to 27.3 percent of the country’s total imports. By contrast, Afghanistan’s exports to Iran amounted to approximately $52.16 million. This asymmetry demonstrates the predominance of Iran’s role as a supplier. However, the increase in Iran’s share of the automotive parts market and the decline in its share of diesel and gasoline indicate differences in the country’s competitive position across commodity markets. Therefore, assessing the sustainability of this position requires examining the composition of trade and changes in market share at the level of individual products and competitors.
Accordingly, the study proposes organizing selected value chains within a clearly defined contractual framework among the Afghan supplier, the Iranian processing unit, the logistics service provider, and the buyer in the third-country market before the raw material enters the process. Under this model, the private sector assumes responsibility for supply, production, and sales; the government, through economic diplomacy, pursues the removal of cross-border barriers; and chambers of commerce facilitate the identification of reliable partners and the formation of consortia. For decision-makers, the outcome of this approach is the identification of markets in which existing positions need to be preserved, priorities for production cooperation, and the operational requirements that must be addressed before capital is committed. The criterion for this assessment will be the share of value added captured by the Iranian firm and its ability to retain that share within the value chain.
مریم کاظمی فرمتهور
نظرات کاربران